SecurityWeek reported on October 12, 2026 that Oleg Korniev pleaded guilty in a U.S. case tied to Your Mule Cashout, a cybercrime money-laundering network. The Justice Department said the network recruited more than 15,000 U.S.-based money mules and laundered at least $10 million stolen from more than 750 U.S. bank accounts.
For a New Jersey business owner, the lesson is not to become an expert in international money laundering. It is to notice how quickly stolen funds can move once an attacker has account access, a convincing story, and someone ready to receive and forward the money. That is where money mule payment fraud becomes an operations problem, not just a bank problem.
Payment Fraud Is An Approval-Control Issue
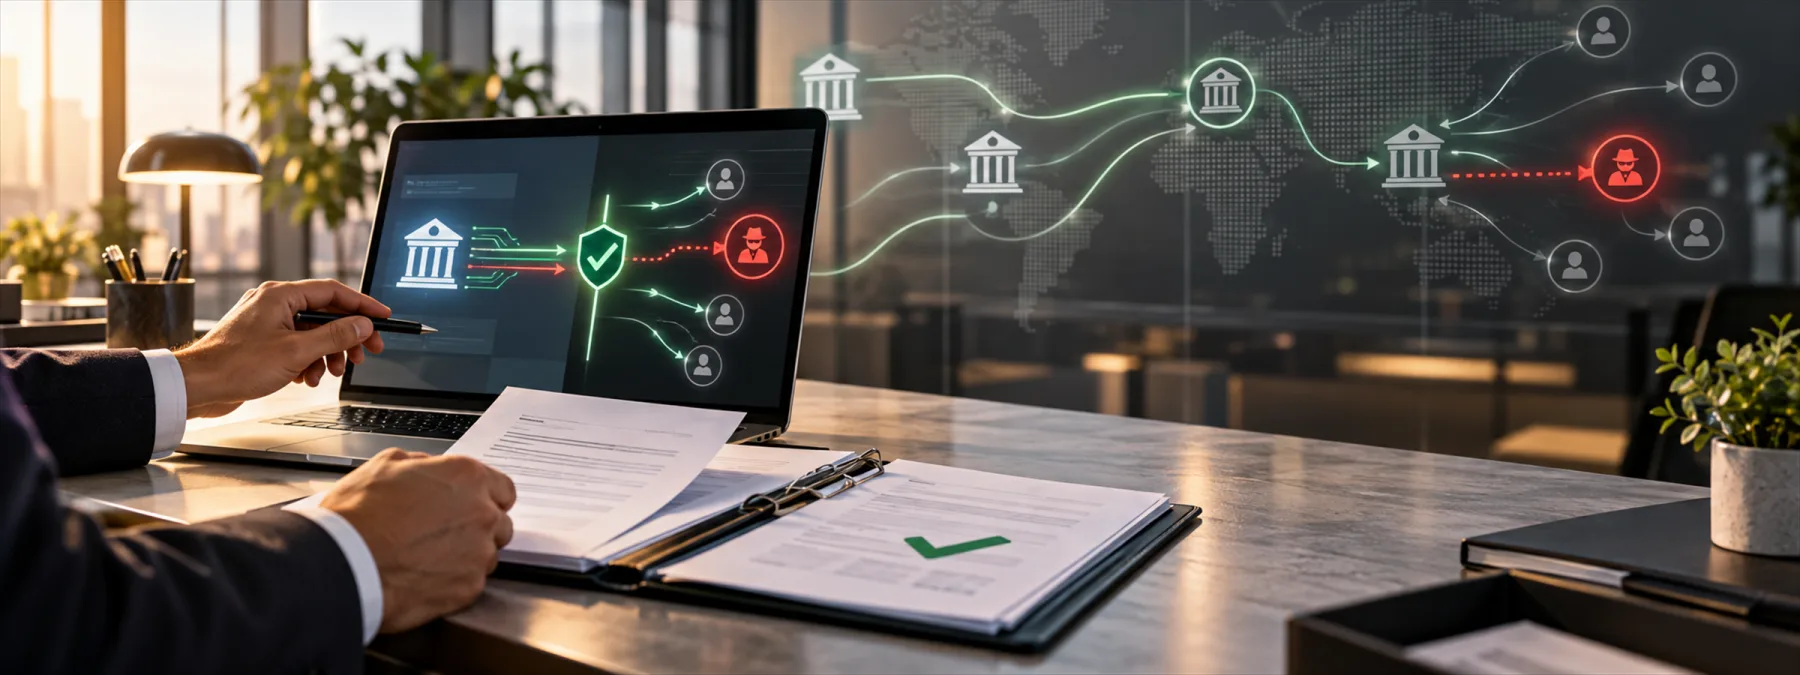
Many small businesses have clear approval rules for large purchases but much softer rules for urgent payments, vendor bank changes, ACH updates, and wire requests. That gap is exactly where cybercrime workflows become practical. A compromised mailbox, fake invoice, rushed executive request, or changed vendor account can push money out before anyone has time to ask whether the request was real.
The right response is not panic. It is a calmer payment process. Owners should know who can approve outgoing payments, who can change vendor banking information, who can override normal timing, and who is responsible for calling the bank when something looks wrong.
Questions To Ask Before The Next Transfer
- Who approves bank-account changes? Vendor banking updates should require a second person and confirmation through a known phone number or portal, not the contact information inside the request.
- Which payments need dual approval? Wires, ACH batches, emergency vendor payments, payroll changes, and refunds deserve clear thresholds and documented signoff.
- How are unusual requests verified? A payment that changes timing, destination, amount, or payment method should trigger out-of-band confirmation.
- What is the bank escalation path? Staff should know who can call the bank, what information to provide, and how fast a recall or fraud report must happen.
- Where is the evidence kept? Approvals, call notes, vendor confirmations, and account-change records should be easy to find during a dispute or insurance review.
A Practical Next Step
Pick one payment workflow this week and trace it from request to approval to bank submission. If one person can receive the request, approve it, change the destination, and release the funds without an independent check, the process is doing too much on ਵਿਹਾਰਕ IT ਸਲਾਹ.
For many businesses, the most useful improvement is simple: document the approved payment path, require independent confirmation for bank changes, and test whether staff know how to pause a questionable transfer. Payment controls are not glamorous, but neither is explaining why the ledger learned a new magic trick.
Sources and further reading