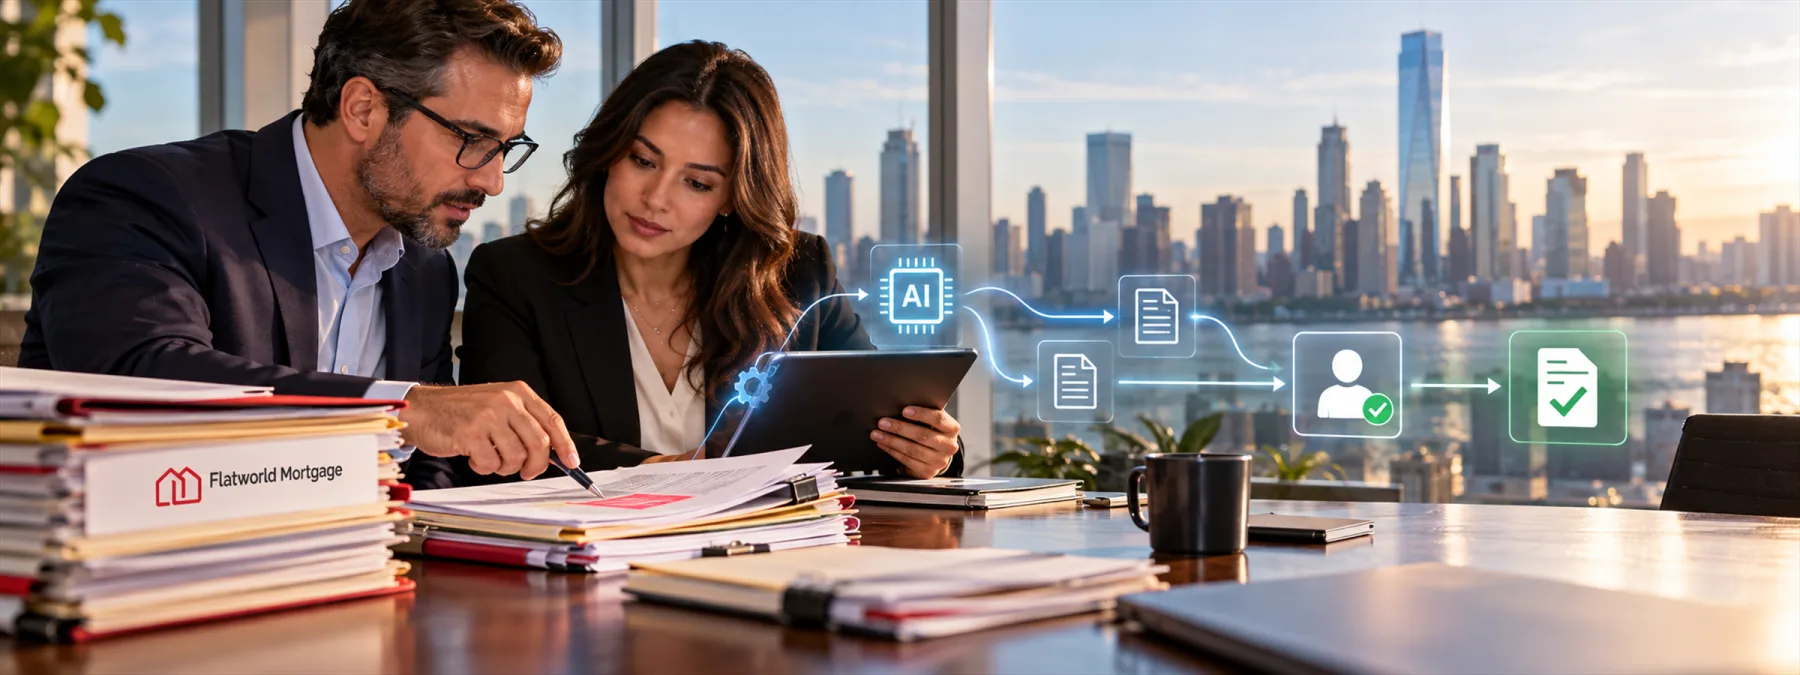
Flatworld Mortgage Solutions LLC, a Princeton, New Jersey-based mortgage operations provider, announced a relaunch today built around automation and agentic AI across loan intake, processing, underwriting support, quality control, closing, and servicing. The company says its model includes defined human checkpoints before automated outputs become lending decisions.
That detail matters more than the AI label. In a regulated workflow, speed is helpful only if the business can still explain what happened, who reviewed the exception, what evidence was retained, and who remained accountable. AI can move a file faster, but the file still needs an owner.
The business risk is not just automation
For New Jersey lenders, finance teams, professional services firms, healthcare practices, schools, and other organizations using outside providers, the practical question is whether AI-enabled work is being governed as a business process or merely purchased as a tool. A vendor can say that an AI workflow is smart, secure, and scalable. The owner still needs to know what those words mean in daily operations.
Flatworld says its platform uses automation and agentic AI inside mortgage workflows, with human-in-the-loop checkpoints and auditable review points. That is the right kind of conversation for any regulated workflow automation project. The value is not only that work may happen faster. The value is that the business can see where judgment, exception handling, and accountability remain attached to a person or team.
Where owners need clarity
The risk with mortgage AI human review, or any AI workflow checkpoint, is that responsibility can become fuzzy. A task may pass through a vendor platform, an internal system, an offshore operations team, an AI agent, and a human reviewer before a customer ever sees the result. If something goes wrong, the business cannot wait until then to learn who had authority.
Before approving an AI-enabled operations provider, owners should request a plain-language workflow map. It should show which steps are automated, which steps are reviewed by people, which decisions are never automated, and which records prove that the review happened. This is especially important for lending, insurance, healthcare, finance, HR, legal, and other work where customer-impacting decisions carry compliance, fairness, privacy, or contractual obligations.
Questions to ask the vendor or internal team
- Which tasks may AI complete without review? Separate document handling, data extraction, routing, recommendations, and final decisions.
- Where is human review mandatory? Look for named checkpoints, not general assurances that people are involved.
- What creates an exception? Ask what confidence scores, missing documents, policy conflicts, customer complaints, or unusual patterns trigger escalation.
- What audit records are retained? The business should know whether prompts, outputs, source documents, reviewer actions, timestamps, and overrides are available later.
- Who owns the outcome? The answer should identify the accountable business role, not just the software or service provider.
- How is sensitive data handled? Confirm access controls, retention, vendor subcontractors, certification scope, and whether customer data trains or improves models.
- How are mistakes corrected? Ask how errors are reported, traced, fixed, and prevented from repeating across similar files.
A practical next step
If your business is already using AI in a regulated operation, choose one workflow this week and trace it from request to final approval. Do not start with a policy document. Start with an actual file, ticket, application, claim, invoice, record, or customer request.
Then ask your provider or internal team to show the checkpoints. Where did automation act? Where did a person review? What did the reviewer see? What was logged? What would have happened if the system was wrong, incomplete, or uncertain?
For a business owner, that review is more useful than a glossy AI feature list. It turns agentic AI lending workflows and other AI-enabled operations into something manageable: a set of approvals, evidence, exceptions, and responsibilities that can be reviewed before they become a customer problem.
Sources and further reading